



Group Envisions Acquiring 14 Companies Including JYP and Japan’s Avex; Unlisted Investment Firm Fails to Disclose Financials
Roughly ₩8300 Billion Required to Secure a 50% Stake; SEC Filing Reports Zero Investors
Nexroc, the overseas investment group that recently announced a public tender offer for JYP Entertainment (035900) shares, has now unveiled an ambitious takeover blueprint targeting 14 companies. Having previously stated its intention to buy a 50% stake in JYP—a transaction requiring over ₩800 billion—the group has now set its sights on major Japanese entertainment firms as well. Yet, with no official talks initiated with JYP and a stark lack of publicly available financial data regarding the group, market doubts are growing over whether Nexroc possesses the financial muscle to back its cascading series of acquisition announcements.
Beyond JYP to Japan’s Avex: What is Nexroc?
In an investor letter published on its official website on October 29, Nexroc outlined its corporate acquisition and integration strategy for the next 18 months. The Korean-language letter stated that a total of 14 companies are under review for acquisition, prominently naming JYP and Japan’s Avex. Avex is a leading Japanese entertainment conglomerate spanning music production and distribution, artist management, and live entertainment.
Nexroc stated that it would deliver private, preliminary proposals to target companies by November 2 and engage in a 60-day negotiation window, with a possible 30-day extension if necessary. The group also set a target to secure a 51% stake in at least two financial and cultural sector firms within the next 12 months.
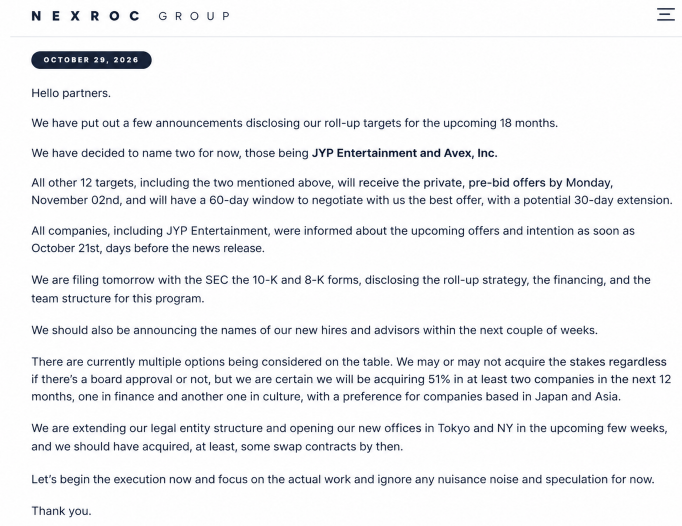 [Source: Nexroc. From the October 29 investor letter citing JYP and Japan's Avex as acquisition targets.]
Describing itself as an unlisted investment group launched in February of this year, Nexroc lists its headquarters in New York and Tokyo. It explains that it maintains corporate entities in the state of Delaware, Japan, and Guernsey, located between the UK and France.
Guernsey is an offshore financial center boasting a basic corporate tax rate of 0%. It is a jurisdiction utilized not only by international investment funds and holding companies, but also by special purpose vehicles (SPVs) established solely to hold assets or execute transactions without separate operational organizations. While the establishment of such entities is entirely legal, further verification is required regarding the actual business activities, asset scales, and ultimate ownership structures of Nexroc’s various corporate vehicles.
Although Nexroc lists asset management, insurance, pensions, and corporate acquisitions as its core businesses, it has failed to disclose group-level financial statements or the specific scale of its assets under management. Past acquisition records are also difficult to verify sufficiently through public data alone. More important than the mere fact that it maintains entities across multiple countries is whether the group can substantiate its financial capacity to execute transactions worth hundreds of billions of won.
Crucially, discussions have not even begun with JYP, the very first takeover target named. In an official statement on October 29, JYP stated, "We have neither received nor reviewed any officially valid proposal." The company explained that emails supposedly sent by Nexroc failed to meet sender reliability standards, categorized as "blatant spam," and were forcibly blocked by mail service providers from ever reaching the company’s servers.
In contrast, Nexroc claimed in its investor letter on the same day that it had sent advance notices to target companies, including JYP, starting October 21. While Nexroc has continuously trumpeted its acquisition plans, no formal proposal has actually been delivered to the target company itself.
Where Will Up to ₩830 Billion Come From? SEC Filing Lists Zero Investors
On October 26, Nexroc and SVCV announced they were reviewing a plan to conduct a public tender offer for 25% to 50% of JYP's issued shares. The proposal suggested adding an approximate 30% premium to the benchmark stock price, targeting November 20 as the launch date for the tender offer.
Adding a 30% premium to the October 26 closing price of ₩36,000 just prior to the announcement yields a per-share acquisition price of ₩46,800. Based on this figure, securing a 50% stake would require roughly ₩830 billion. The actual purchase price and calculation methodology have yet to be finalized.
Doubts regarding the group's financial backing have been raised internationally as well. Reuters reported on October 27, citing data from financial information provider PitchBook, that Nexroc’s most recent fundraising round amounted to $25 million—less than one-twentieth of the approximately $530 million market value of a 50% stake in JYP at the time.
Questions also linger over a private securities offering statement filed with the U.S. Securities and Exchange Commission (SEC) by Nexroc-affiliated entity NEXROC SVCV. The company reported issuing and fully selling a total of $50 million in securities, yet the same filing recorded the number of participating investors as zero. Because the SEC does not guarantee the accuracy of filing contents, additional verification regarding actual capital inflows and counterparties remains necessary.
Past fundraising figures or the number of investors listed in a regulatory filing do not definitively preclude a firm's takeover capabilities. The possibility remains that additional capital could be raised through external investors or financial institutions, but concrete data supporting this has yet to be released.
Despite the lack of substance, share prices reacted immediately to the announcements. JYP shares rose 11.25% over two days, climbing from ₩36,000 on October 26 prior to the announcement to ₩40,050 on October 28. Market capitalization surged purely on acquisition expectations, even without a formal tender offer statement being filed.
Tender offers are typically executed through formal regulatory filings after finalizing financing and purchase terms. Nexroc, however, announced its acquisition intent without disclosing final pricing or funding details. Independent analyst Douglas Kim, cited by Reuters, expressed concern that such pre-announcement tactics could set an unfavorable precedent in the Korean stock market.
South Korea's Financial Supervisory Service (FSS) has also noted that expressing acquisition intent via press release prior to filing a formal tender offer statement is highly unusual, and is currently monitoring the situation for potential unfair trading and regulatory violations. To date, no official announcement has been made confirming any suspected unfair trade practices.
Nexroc stated it would submit documents detailing its takeover strategy and funding plans to the SEC on October 30, and deliver preliminary proposals to target companies by November 2. Its target launch date for the JYP tender offer remains November 20. Whether these cascading takeover announcements will translate into actual transactions will likely depend on the disclosures and subsequent procedures rolled out in accordance with these timelines.



