



Third-quarter operating profit reaches 90.8 billion KRW, missing consensus by 30%; stock price tumbles over 7%
Unspecified impact of foreign exchange fluctuations and deferred revenue; focus shifts to fourth-quarter recovery
Despite the ongoing boom in the High Bandwidth Memory (HBM) market, a key equipment supplier has failed to meet earnings expectations. Hanmi Semiconductor (042700) reported a third-quarter operating margin exceeding 50%; however, both its revenue and operating profit fell approximately 30% short of the analyst consensus formed in early October. While the company attributed the shortfall to unfavorable exchange rate fluctuations and the deferral of certain equipment sales to the fourth quarter, it did not disclose the specific financial impact of these factors.
The company’s share price saw a sharp decline on the day of the announcement. As of 11:30 a.m. on the 30th, Hanmi Semiconductor was trading at 181,600 KRW, down 7.77% from the previous trading session, amid heavy selling pressure from institutional and foreign investors.
Operating margin exceeds 50%, yet misses profit target by 30%
Hanmi Semiconductor announced preliminary consolidated third-quarter results, reporting revenue of 181 billion KRW and an operating profit of 90.8 billion KRW. While this represents a year-on-year increase of 8.9% and 33.9%, respectively, it marks a sequential decline of 27.9% in revenue and 30.3% in operating profit compared to the previous quarter.
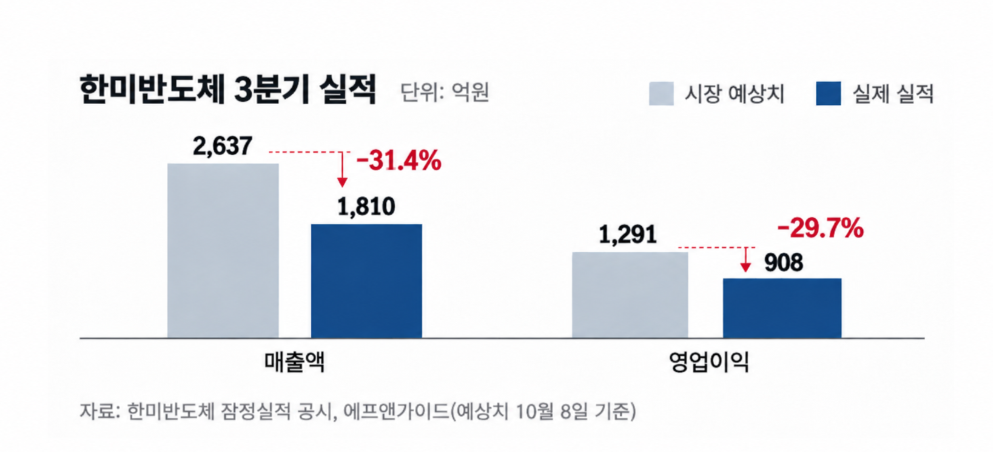 According to FnGuide data from October 8, the market consensus had projected revenue of 263.7 billion KRW and an operating profit of 129.1 billion KRW. The actual results fell short by 82.7 billion KRW (31.4%) and 38.3 billion KRW (29.7%), respectively—a significant gap for a market that had anticipated surging equipment orders driven by the transition to HBM4.
The operating margin stood at 50.2%, up 9.4 percentage points from the same period last year. While the company maintained high profitability centered on its high-value thermal compression (TC) bonders, the overall volume of revenue failed to meet expectations.
Cumulative revenue for the first nine months of the year reached 483.1 billion KRW, down 2.1% from the same period last year, while operating profit rose 2.6% to 229.6 billion KRW. Despite the growth in profit, revenue has yet to return to the levels observed last year.
Revenue recognition for semiconductor equipment can fluctuate depending on customer inspection schedules following delivery. Whether the company’s explanation regarding deferred revenue and exchange rates fully accounts for the 82.7 billion KRW discrepancy remains unclear. Furthermore, it remains to be seen whether the recognition of deferred revenue in the fourth quarter will be sufficient to restore the equipment supply volume originally projected by analysts.
Fourth-quarter target set at 150 billion KRW; full recovery remains uncertain
Hanmi Semiconductor projects a recovery in the fourth quarter, fueled by the spillover of deferred equipment revenue and expanded shipments to overseas clients. The company aims to achieve its highest quarterly revenue to date, potentially marking its third consecutive year of record-breaking annual revenue.
With annual revenue of approximately 576.7 billion KRW last year and year-to-date revenue of 483.1 billion KRW, the company requires roughly 93.7 billion KRW in the fourth quarter to surpass its previous annual record. Reaching the quarterly record of 149.6 billion KRW achieved in late 2024 would effectively secure this annual milestone.
However, there is a clear disconnect between the company’s internal goals and the level of performance investors had expected. Even if the company achieves its goal of 150 billion KRW in the fourth quarter, it falls significantly short of the 263.7 billion KRW in revenue that the market had initially anticipated for the third quarter alone.
The expansion of investment in the HBM sector remains a significant opportunity for Hanmi Semiconductor. As industry leaders like SK hynix and Micron expand their next-generation HBM production capacity, demand for TC bonders used in stacking processes is expected to rise. Hanmi Semiconductor is currently diversifying its product lineup, incorporating new TC bonders for large-area AI semiconductor packaging and flip-chip (FC) bonders alongside its HBM4-compliant equipment.
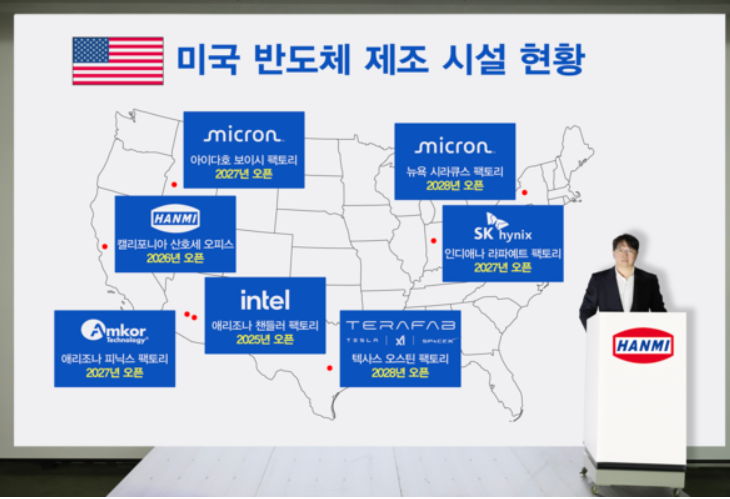
The establishment of "Hanmi USA" in San Jose, California, this month is a strategic move to strengthen ties with overseas clients. As competitors like Hanwa Semitek expand their TC bonder supply, the ability to secure new customers and maintain volume with existing ones will be the key determinant of future financial performance.
Hanmi Semiconductor’s path to a fourth-quarter rebound remains contingent upon whether the deferred volumes are successfully recognized as revenue. Furthermore, the company must ramp up the supply of new equipment to approach the growth trajectory that the market had originally anticipated.
[SOURCE]


