Store counts decline and revenue growth slows; industry shifts toward 'qualitative growth' focused on high-performing outlets.
BGF Retail's operating profit surpasses 100 billion won for the first time; GS25 sees an 8% decline due to inventory losses.
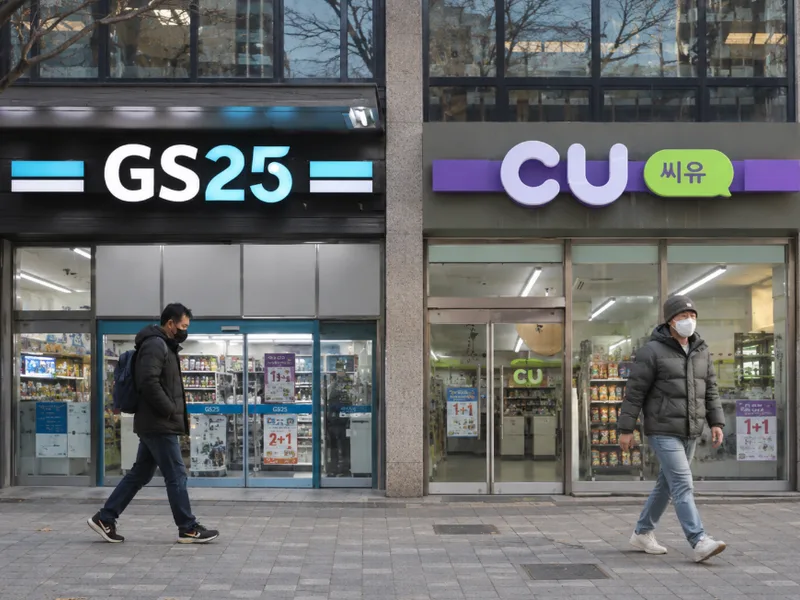
The growth strategy of South Korea's convenience store industry, which has long relied on increasing store counts to scale, is undergoing a fundamental shift. With market saturation leading to a year-on-year decline in total store numbers and a slowdown in per-store revenue growth, the limitations of the expansion-focused model have become clear. Industry leaders CU and GS25 are now prioritizing selective openings of high-performing stores, attracting foreign customers, and strengthening fresh food and quick-commerce services to boost the profitability of existing locations.
According to data from the Ministry of Trade, Industry and Energy and industry aggregates, the total number of stores for the four major chains—GS25, CU, 7-Eleven, and E-mart 24—stood at 53,348 as of September, a 0.7% decrease compared to the same period last year. While this is a slight increase from the 53,266 stores recorded at the end of last year, the era of rapid expansion through new openings has effectively ended.
Although per-store revenue remains positive, the pace of growth has noticeably decelerated. Per-store revenue growth, which ranged from 3.9% to 8.1% in the first half of this year, slowed to 1.5% to 3.6% in the third quarter. Overall industry revenue growth also cooled from 4.8% in the second quarter to 1.6% in the third, partly due to base effects from last year's consumer voucher distributions and weather-related factors.
Amid these conditions, the third-quarter performance of industry leaders CU and GS25 diverged in terms of profitability. BGF Retail, the operator of CU, reported consolidated revenue of 2.5152 trillion won and an operating profit of 100.8 billion won, marking year-on-year growth of 2.1% and 3.2%, respectively. This marks the first time the company has exceeded 100 billion won in quarterly operating profit.
Conversely, GS Retail's convenience store division, GS25, saw revenue rise 1.1% to 2.4743 trillion won, but operating profit fell 8.1% to 78.2 billion won. However, this was largely due to a one-time 9.4 billion won loss related to over-purchased inventory. Kiwoom Securities estimated that excluding this factor, operating profit would have risen by approximately 3% year-on-year to 87.6 billion won.
Foreign customer revenue surges by 60%; focus on differentiated products and quick-commerce
Key drivers for revenue growth at both companies include demand from foreign tourists and differentiated product offerings. In the third quarter, revenue from foreign customers surged by 66.8% for CU and 69.4% for GS25 compared to the same period last year. Notably, foreign customer revenue accounted for 35.5% of CU's total store revenue growth in the third quarter. GS25 also captured local demand, with quick-commerce revenue—combining delivery and pickup services—growing by 86.9%.
Financial analysts are increasingly focusing on strategies that prioritize individual store productivity over total store count. Kim Na-mi, an analyst at Mirae Asset Securities, noted in an October 30 retail report that "even in a situation where store growth is more limited than in the past, if the productivity of new stores increases, the expansion itself can contribute to profits. The focus of future growth is shifting from the number of stores to per-store revenue and the productivity of existing locations."
In practice, both companies are focusing on enhancing the profitability of existing stores rather than aggressive expansion. CU is strengthening its private label (PB) products, desserts, and processed foods, which offer higher margins, while continuing to open only high-performing stores. GS25 is enhancing the competitiveness of its existing network by expanding fresh food offerings, quick-commerce, and stores specialized for foreign customers, while closing inefficient locations.
Beyond securing foreign customers and differentiated products, the ability to efficiently manage inventory and operating costs is expected to widen the profitability gap among convenience store operators.