IEA projects a shift to supply surplus in Q4 as Middle East crude exports recover.
European diesel prices remain 77% higher than pre-war levels amid persistent export disruptions for refined products.
While global oil supply has begun to exceed demand for the first time since the onset of the conflict in Iran due to a recovery in Middle East crude exports, diesel supply remains critically tight. This divergence stems from the rapid restoration of crude shipments compared to the sluggish recovery in exports of refined products like diesel. Consequently, while crude oil prices have fallen significantly, diesel prices remain elevated.
In its November oil market report released on the 13th (local time), the International Energy Agency (IEA) projected that the global oil market would shift to a supply surplus in the fourth quarter of this year. According to Reuters, supply is expected to exceed demand by an average of approximately 1.7 million barrels per day in the fourth quarter—a reversal from the IEA's previous forecast of a supply deficit.
Crude Prices Drop 32% While Diesel Falls Only 11%
The price gap between crude and diesel has widened significantly. According to the IEA, North Sea spot crude prices fell 32% from $136 per barrel on the 8th of last month to approximately $93 at the time of the report. During the same period, European diesel prices declined by only 11%, remaining at roughly $180 per barrel—still 77% higher than pre-war levels.
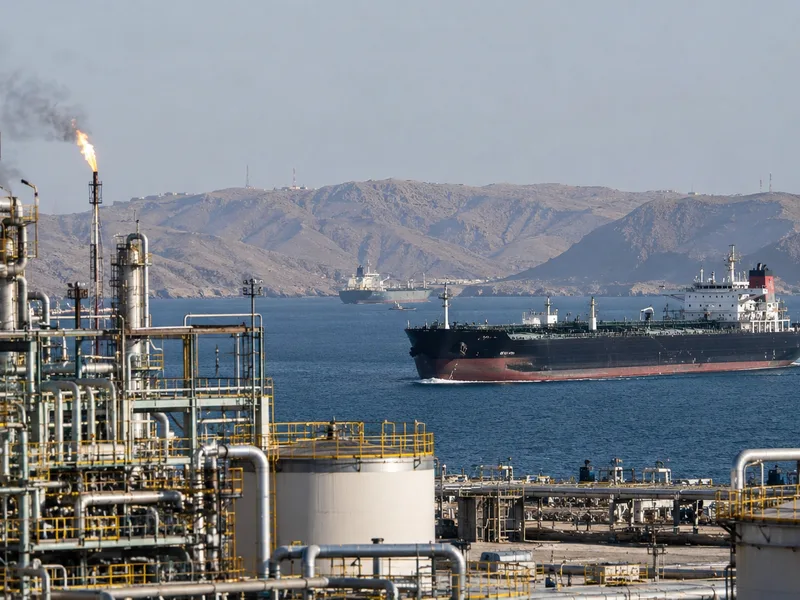
The decline in crude prices is driven by the recovery in Middle East exports. Excluding Oman, crude exports from the Gulf region in October reached 15 million barrels per day, recovering to 82% of pre-war levels.
Refined Product Export Disruptions Sustain Diesel Strength
Conversely, exports of refined products and liquefied petroleum gas (LPG) from the Gulf remain at half their pre-war levels, explaining the relative strength of diesel prices. Unlike crude oil, refined products have limited alternatives to the Strait of Hormuz. While Saudi Arabia and the UAE utilize pipelines to transport crude to the Red Sea and the Gulf of Oman, these pipelines do not carry refined products. According to the United Kingdom Maritime Trade Operations (UKMTO), only 308 vessels traversed the strait between the 5th and 11th of this month, approximately 65% fewer than pre-war levels. Furthermore, ongoing attacks on Russian energy facilities have curtailed the supply of Russian diesel to the international market.
Inventory data reflects this trend. Global oil inventories rose by 52 million barrels in October, driven by an 86-million-barrel increase in oil at sea due to the recovery in Middle East crude exports. Meanwhile, onshore inventories have continued to decline, reaching their lowest level since at least 2016. Oil stocks in OECD member countries also fell by 47 million barrels.
Boosting Supply Through Increased Refining and Strategic Reserves
Efforts to bridge the supply gap are underway. The IEA expects global refinery crude throughput to rise from 81.3 million barrels per day in October to 84.7 million barrels in December. Refiners in the Atlantic basin, including the U.S., are maximizing operations to capture high refining margins. In Asia, analysts suggest that improved crude access and China's new export quotas for petroleum products could support production growth, though high freight costs for Middle Eastern crude remain a significant burden for Asian refiners.
While refinery production recovers, emergency strategic reserves are expected to compensate for the shortfall. IEA member countries plan to release approximately 71 million barrels of strategic reserves by the end of February next year, including about 15 million barrels of diesel. If executed as planned, cumulative releases will reach approximately 420 million barrels, exceeding the 400-million-barrel maximum announced by the IEA in March.
Diesel Surplus Expected Early Next Year, but Inventory Recovery Remains Slow
There is potential for diesel shortages to ease, as high prices have dampened demand. The IEA previously estimated that global diesel demand in the fourth quarter would fall by 1 million barrels per day year-on-year. The latest report attributes the slow recovery in automotive fuel demand to high prices, the adoption of electric vehicles, and improved fuel efficiency. As demand grows slowly, it provides time for supply to catch up.
The IEA projected last month that the diesel market would return to a surplus in the first quarter of next year as refinery production increases. However, even if supply exceeds demand, it will be insufficient to replenish the inventories depleted this year, making a full recovery unlikely before the second half of next year.
Outlook for Next Year: Rising Supply and Diesel Price Variables
The IEA forecasts that global oil supply will reach 108.1 million barrels per day next year, an increase of 6.6 million barrels per day from this year, while demand growth is expected to be limited to 2 million barrels per day. If supply grows faster than demand, downward pressure on international oil prices may intensify.
However, diesel prices will be influenced not only by crude supply conditions but also by the normalization of refined product exports and the speed of inventory replenishment. If attacks on shipping continue—a key risk factor identified by the IEA—and the Strait of Hormuz remains disrupted, combined with ongoing issues in Russian refined product exports and delayed inventory replenishment, the decline in diesel prices may remain limited even if crude prices fall.