Cumulative Q3 revenue up 27%, operating profit up 62%... Significant improvement in profitability.
North American equipment supply in full swing... Shareholder returns bolstered by treasury stock cancellation and 4 billion won dividend.
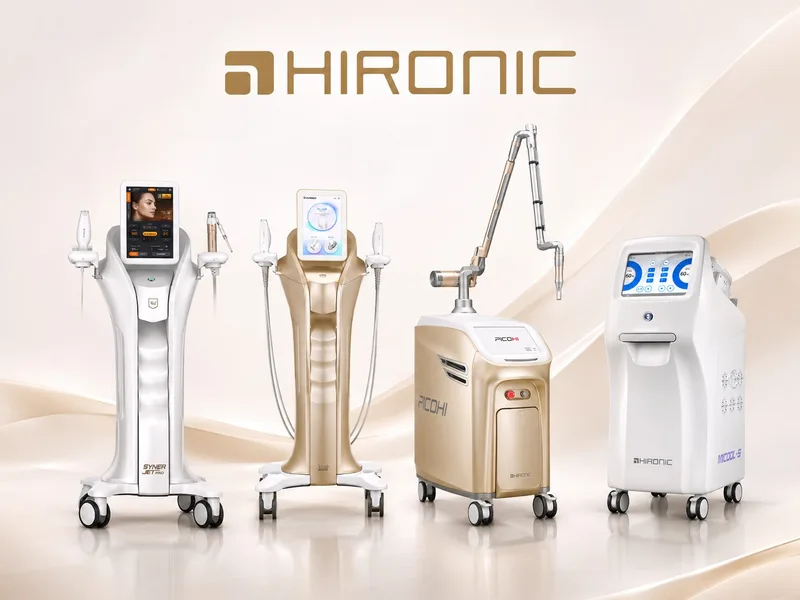
Hironic (149980), a company specializing in medical aesthetic devices that previously endured a prolonged trading suspension, is accelerating its efforts to restore corporate value. Since the resumption of trading in May, the company has demonstrated clear performance improvements and is laying the foundation for a rebound through entry into the North American market, treasury stock cancellation, and dividend payouts.
For the first three quarters of this year, Hironic reported cumulative consolidated revenue of 30.05 billion won and an operating profit of 3.88 billion won, marking increases of 26.9% and 61.9%, respectively, compared to the same period last year. Net profit also surged by 160.4% to 2.86 billion won. Both revenue and operating profit reached record highs for the first nine months of the year.
Profit Growth Outpaces Revenue; Full-Scale North American Entry
A notable aspect of Hironic's performance is the improvement in profitability. The cumulative gross profit margin for the third quarter rose from 54.9% last year to 65.6% this year. Despite the increase in revenue, the cost of sales actually decreased, leading to an improvement in the operating profit margin from 10.1% to 12.9%.
The new growth engine is the North American market. In July, Hironic signed an exclusive distribution agreement with global medical aesthetic device firm Venus Concept for the United States and Canada.
Following U.S. Food and Drug Administration (FDA) 510(k) clearance, the company shipped 20 units of its North America-specific model based on the 'New Doublo 2.0' in August and approximately 40 units in September, with follow-up orders for equipment and consumables continuing to arrive.
Given the business model, which generates recurring revenue from consumables such as cartridges and tips after the initial equipment sale, the expansion of installations in North America is expected to serve as a driver for mid-to-long-term growth and profitability.
Rapid Growth in Home Beauty; Subsidiary Profitability Remains a Challenge
The company is also expanding its business scope from medical devices for hospitals and clinics to the personal home beauty market.
Cumulative revenue for the home beauty subsidiary, HomeThera, reached 5.94 billion won in the first three quarters of this year, exceeding its total annual revenue of 4.36 billion won from last year by over 36% in just nine months.
However, it is necessary to distinguish between top-line growth and profit contribution. HomeThera recorded a cumulative net loss of 840 million won in the third quarter, while its domestic distribution subsidiary, Hironic Korea, posted a net loss of 1.16 billion won.
Whether these subsidiaries can improve their profitability will be a critical variable for future consolidated earnings growth.
Enhancing Shareholder Value via Stock Cancellation and Dividends
Alongside performance improvements, the company is working to restore trust in the capital markets.
Hironic’s trading was suspended in April of last year due to a qualified audit opinion on its 2024 financial statements. However, after securing an unqualified opinion and being cleared by the Korea Exchange’s listing eligibility review, trading resumed on May 4.
The company completed a third-party capital increase of approximately 13.2 billion won in January of this year and cancelled all 4 million shares of its treasury stock in June. In July, it implemented its first-ever quarterly dividend of 233 won per share, totaling 4 billion won.
As of the end of September, cash, cash equivalents, and short-term financial instruments stood at approximately 17.9 billion won, up from 4.9 billion won at the end of last year. In addition to the capital raised through the issuance of new shares, the company's cumulative operating cash flow for the third quarter turned from a 620 million won outflow last year to a 1.87 billion won inflow this year.
However, uncertainty remains regarding ongoing litigation with Blue Core Company concerning the cancellation of general meeting resolutions and the invalidation of new share issuances.
Having overcome the crisis of a trading suspension, Hironic has now entered a phase where it must prove both its growth potential and profitability. The key to future revaluation will be whether North American equipment supply leads to expanded recurring revenue from consumables and whether the growth of its home beauty subsidiaries translates into improved profitability.